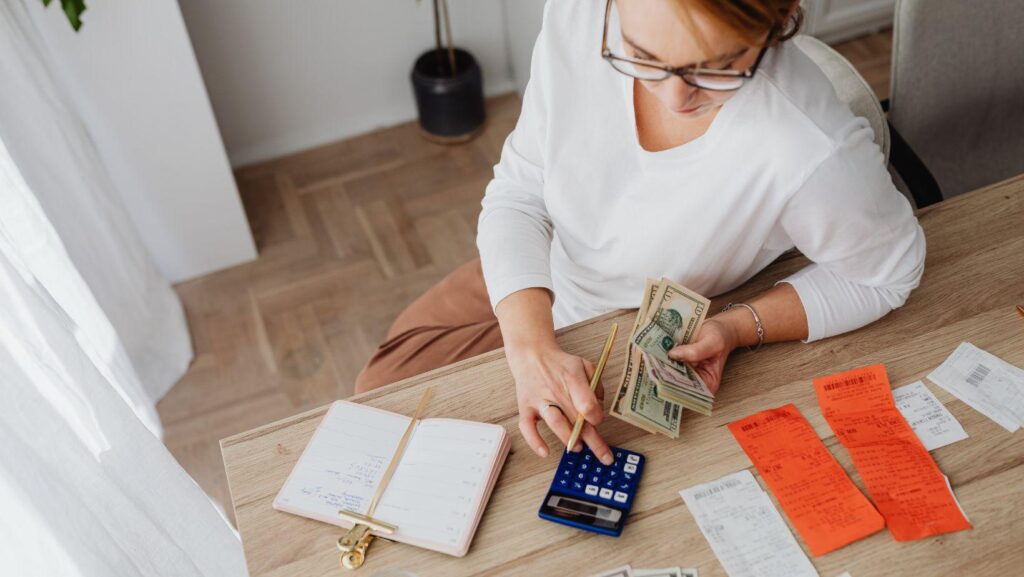
A budget helps you take control of your money, but having one doesn’t necessarily mean financial success. An effective financial plan is the one that supports your current and future goals. Even minor budgeting mistakes can make it harder to save, invest, manage debt, or prepare for unexpected expenses.
Learning from these errors can help build a more realistic plan. This article goes through five budgeting mistakes that could stand between you and your long-term financial goals.
Focusing Only on Monthly Expenses
While bills and everyday spending are important, your financial plan should also account for costs and goals that extend beyond the present. For example, you may want to plan as soon as possible for the following:
- Education expenses
- Big purchases
- Home repairs and maintenance
- Emergency funds
Overlooking these expenses can leave you straining or end up in debt when they eventually arise. Make a monthly budget a part of your larger financial plan. When setting money aside for immediate needs, include future priorities too.
Waiting Before Starting Saving for Retirement
Retirement may seem far, but the sooner you start, the better. Those small contributions will add up over time, growing your savings. When you delay retirement savings, it can be harder to build sufficient funds later.
You can utilize your employer-sponsored retirement plan or set up an individual retirement account. You can also increase contributions as your income rises. The important point is to make retirement savings a regular part of your financial plan rather than something you intend to start once you have extra money.
Not Considering Life Insurance
While not many will consider life insurance when creating a budget, it can be an important part of long-term financial planning, especially if you have dependents. This is because lost income and an unexpected death could leave them facing expenses such as housing costs, debts, education, or daily living expenses.
Different insurance policies vary depending on your specific needs. You can choose from whole life insurance, term life insurance, or universal life insurance depending on your needs. When making a selection, your aim should not be adding another expense but to account for potential financial risks that could otherwise undermine your long-term plans.
Setting Unrealistic Spending Limits
An extremely restrictive budget may look good on paper, but can be harder to maintain. For instance, it will not be easier to eliminate all entertainment expenses and occasional purchases at once.
A sustainable budget should leave some room for enjoyment, but with a limit. This flexibility will allow you to cut these expenses gradually. A realistic budget is the one that gives a clear framework for enjoying your money as you make progress towards your financial goals.
Failing to Review Your Budget Regularly
Your financial situation will change from time to time. A budget that worked well years back may no longer make sense now. Your income can change, household expenses can increase, and new goals can emerge.
Review your spending and financial priorities. Know where your money actually went rather than relying solely on your original estimates. You can make use of budgeting apps or a spreadsheet to compare your actual spending with your planned expenses. This way, if your circumstances have changed, it will be easier to identify and make some adjustments.
Endnote
A good budget tells you more than how much you can spend monthly. It makes it easier to make decisions that support your larger financial objectives. Avoid treating your budget as a fixed plan. You have to review it regularly as your circumstances and goals change. Your budget can become a practical tool for building greater financial stability only with consistent adjustments and realistic expectations.